
How do you finance a geodesic dome?
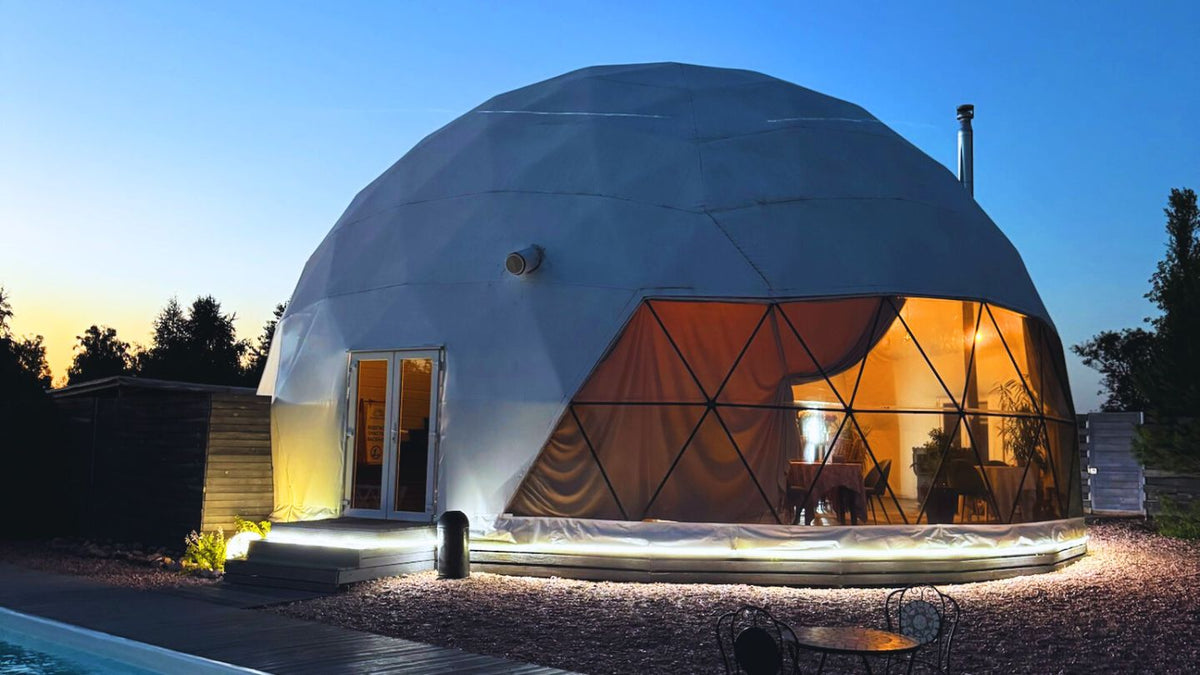
Yes, you can finance a geodesic dome, and most people who buy one do. Three paths cover nearly every situation: home improvement or personal lending for one or two structures, a specialty outdoor hospitality lender for a small glamping build, and an SBA-backed business loan for a site that will earn revenue.
Which one fits comes down to two things: how many domes you are putting up, and whether the project makes money. Here is how each path works, what it suits, and what to have ready so the conversation goes quickly.
How to finance a geodesic dome: three paths
1. Home improvement or personal lending. This is the common route for one to a few structures: a backyard studio, an ADU, a guest suite, a first rental unit. Our lending partner starts with a soft credit check to show your options, so seeing what you qualify for leaves your score alone. Funds are unsecured and arrive quickly, which suits a buyer who wants the dome ordered this month. How to think about it: this path trades a slightly higher rate for speed and simplicity, and on a purchase in the $10,000 to $40,000 range that trade usually pays off.
2. Specialty outdoor hospitality lenders. Once you are building several units, a generalist lender starts asking questions it has no framework for. Lenders who work specifically in glamping and outdoor hospitality already understand dome structures, seasonal revenue, and phased builds, so your project gets underwritten on its own merits. How to think about it: once you are past two or three units and the site itself is the business, start here.
3. SBA-backed business loans. For campgrounds, RV parks, resorts, and glamping sites, SBA 7(a), 504, and Express programs, along with USDA lending, exist for exactly this kind of build. Terms run long and rates are competitive, and the tradeoff is paperwork and a slower timeline. How to think about it: worth it when the number is large and you plan to hold the property, which is why operators building out a full site tend to land here.
All three, with the partners we work with, sit on our financing options for a dome build page so you can compare them side by side. Rates and terms depend on your credit, your project, and the lender, so treat these paths as a map rather than a quote.
What you are actually financing
Lenders want a number, and a vague one stalls an application. Two real figures anchor most dome projects:
| What you are financing | Real Harmony number |
|---|---|
| Dome kit alone (Dome 7, 23 ft across, 415 sq ft) | from $10,125 |
| Guest-ready four-season dome, all in (dome, deck, utilities, interior, freight, permitting) | roughly $60,000 to $90,000 |
The kit is the easy line. The rest, foundation and utilities and freight and interior fit-out, is what turns a shell into a place someone can live in or rent, and it is the part first-time buyers leave out of the loan request and then have to go back for. Ask for the whole project the first time.
Getting ready to apply for dome financing
Four things make the difference between a week and a month:
- An itemized estimate. Configure your exact dome in the dome builder and pull the priced estimate. A line-item number reads as a real project instead of an idea.
- Where the dome is going. Whether you own the land, and whether power and water are close by.
- Site and foundation costs. A contractor ballpark for the deck or concrete pad, plus freight to your address.
- A revenue plan, if it earns. Nightly rate, season length, and unit count are what a hospitality or SBA lender reads first.
Buyers who bring those four get answers in days. It also tends to surface the honest version of the budget early, while you can still choose a smaller dome, a simpler finish, or a phased build rather than discovering the gap halfway through.
Financing a dome you plan to rent
A dome that earns changes the math in your favor. A powder-coated steel frame engineered for a 20-plus year structure gives a lender a long useful life to underwrite against, and a nightly rental rate gives it a repayment story. Bring both, along with the structural study and documentation that come with a Harmony dome, and the project reads as an asset with a plan rather than a purchase.
Start with your number, then pick the path. Build your configuration, get the itemized estimate, and bring it to whichever of the three fits your project.
Can you get a mortgage on a geodesic dome?
It depends on the lender and the appraisal. A dome on a permanent foundation with stamped engineering is a permitted structure like any other, and some lenders will treat it that way. Most buyers use home improvement, specialty, or SBA lending instead, because it moves faster and rests on the project rather than on how one appraiser reads a round building.
Does checking dome financing affect my credit score?
Seeing your options starts with a soft credit check, which leaves your score untouched. A hard pull happens later, only when you choose an offer and move forward with that lender.
Can you finance a dome before you own the land?
For a single dome, yes, since personal and home improvement lending is based on you rather than the property. Project and SBA lending generally want the site settled first, because the land is part of what they are underwriting.
Ready to put a number on it?
Build and price your dome